What If You Could Become Mortgage Free Years Sooner?

Your mortgage may be costing you more time and interest than it needs to. Discover how a smarter mortgage and cash-flow strategy could help reduce the interest you pay, shorten the life of your mortgage and bring your Mortgage Free date forward — without relying on additional repayments.

Australian Owned & Operated

Personalised Mortgage Strategy

Designed to Reduce Interest & Time

Ongoing Support Until Mortgage Free

The Problem

Your Mortgage Could Be Costing You More Than It Needs To.

For most Australians, the mortgage is their biggest financial commitment — and one of the longest. You make your repayments every month. You work hard. You earn more. Yet your mortgage can continue for decades, with a significant portion of your money going towards interest rather than building your financial freedom.

But what if there was a smarter way to use the money you're already earning?

At Amortize Debt, we look at your current mortgage, income, expenses and cash flow to identify opportunities that may help you:

Reduce the interest you pay

Make your existing cash flow work harder

Potentially pay off your mortgage sooner

Build greater control over your finances

Move closer to becoming Mortgage Free

You don't need to guess. You don't need to change your lifestyle overnight. Take our simple Mortgage Freedom Assessment and discover what may be possible based on your own numbers.

The Traditional Path

$800,000 Mortgage

30 Years of Repayments

A Significant Interest Bill

Less Money Working For You

Mortgage Still Hanging Over You

“What if you could use the money you're already earning more efficiently and potentially become Mortgage Free sooner?”

Calculator

Discover Your Amortize Debt Potential

Complete the calculator below and receive an instant estimate of how much sooner you could potentially become Mortgage Free.

*Illustrative example only. Individual results vary and depend on personal circumstances, loan structure, interest rates and financial behaviour and confirmed after undertaking a Full Assessment.

Client Success Stories

Real Australians. Real Results.

Michael & Sarah

Queensland
Mortgage Balance

$720,000

Projected (before)

2052

Projected (after)

2043

Interest Saved

$214,000

Years Saved

9 Years

“We finally feel in control of our finances and see a clear path to becoming Mortgage Free.”

David & Rebecca

Victoria
Mortgage Balance

$950,000

Projected (before)

2054

Projected (after)

2043

Interest Saved

$367,000

Years Saved

11 years

“The Amortize Debt platform changed how we think about money and gave us a plan we can trust.”

Chris & Amanda

New South Wales
Mortgage Balance

$580,000

Projected (before)

2050

Projected (after)

2043

Interest Saved

$146,000

Years Saved

7 years

“We wish we had met the Amortize Debt team sooner. They made the whole process feel easier.”

Why Amortize Debt

A Smarter Path To Mortgage Freedom

We help you understand where your money is going, identify opportunities to improve your cash flow, and build a strategy designed around your goal of becoming Mortgage Free sooner.

GET YEARS BACK

Become Mortgage Free Sooner

Your mortgage doesn't have to follow the traditional 25–30 year path. We identify opportunities that may help you reduce the time it takes to repay your home loan.

KEEP MORE OF YOUR MONEY

Reduce The Interest You Pay

Interest can become one of the biggest costs of owning your home. We look at how your money is working and identify opportunities to potentially reduce the interest charged over the life of your loan.

TAKE BACK CONTROL

Know Where Every Dollar Is Going

Your income, expenses and mortgage don't operate independently. We help you understand your cash flow so your money has a purpose — rather than simply disappearing each month.

YOUR PLAN. YOUR NUMBERS.

A Strategy Built Around You

No two households are the same. Your mortgage, income, expenses, goals and circumstances are unique — so your strategy should be too.

SEE YOUR PROGRESS

Know How You're Tracking

See where you are today, understand the progress you're making and identify opportunities to keep moving towards your Mortgage Freedom goal.

WE STAY WITH YOU

With You Until Mortgage Free

Our support doesn’t end once your strategy is in place. We continue to review, guide, and adapt your plan as life changes, helping you stay focused and on track until the day your mortgage is paid off.

Your mortgage is unique. Your numbers are unique. Let's see what's possible for you.

Show me what's possible

General Questions

Frequently asked questions

1

What exactly does Amortize Debt do?

We help homeowners explore more efficient ways to structure and manage their mortgage and household cash flow, with the objective of becoming Mortgage Free sooner.

Our approach starts with understanding an important principle:

Mortgage interest is generally calculated daily on the outstanding loan balance and charged periodically.

That means the structure of your lending, where your income and available cash are held, and how money moves through your household finances can all matter.

We analyse your mortgage, income, expenses, assets, liabilities and existing banking structure to identify opportunities to potentially make your overall financial structure more efficient.

The objective isn't simply to put more money into your mortgage. It's to make the money you already have work more effectively.

2

How is Amortize Debt different from a traditional mortgage strategy?

A traditional mortgage is commonly structured around making scheduled principal-and-interest repayments over a long loan term.

We look beyond the scheduled repayment.

We examine how your mortgage interest is calculated, how your income enters and moves through your household, where available cash is held, how everyday expenses are managed and whether your existing loan structure is helping or hindering your Mortgage Freedom objective.

Depending on your circumstances, a more efficient structure may potentially reduce the effective interest cost of your mortgage and accelerate your pathway towards Mortgage Freedom.

It's about financial structure and cash-flow efficiency — not simply making bigger mortgage repayments.

3

How can the way banks calculate mortgage interest potentially work in my favour?

This is one of the most important concepts behind our strategy.

Australian home-loan interest is commonly calculated daily based on the relevant outstanding loan balance and then charged to the loan periodically.

That means what happens to your money throughout the month can matter.

If an appropriate loan and offset structure is established, money sitting in an eligible offset account may reduce the amount against which mortgage interest is calculated.

Rather than allowing income and available cash to sit elsewhere without affecting the mortgage interest calculation, we assess whether your cash flow can be structured more efficiently.

Small daily differences can potentially compound into meaningful differences over time.

4

Why is an Offset Account important?

Because an eligible 100% offset account can allow your money to perform two jobs at once.

Your funds generally remain accessible to you, while the eligible balance held in the offset account can reduce the amount of your linked mortgage on which interest is calculated.

For example, if an eligible mortgage balance were $800,000 and $50,000 were maintained in a 100% offset account, interest would generally be calculated as though the relevant balance were $750,000, subject to the particular loan and offset terms.

The important issue, however, isn't simply having an offset account.

It's understanding how to use it effectively as part of an overall cash-flow and lending strategy.

5

Why would Amortize Debt consider changing the structure of my home loan?

Because the cheapest interest rate doesn't necessarily tell you whether your overall mortgage structure is the most effective for your circumstances.

We consider the broader picture, including:

  • Loan structure
  • Interest rate
  • Principal and interest versus interest-only arrangements where appropriate
  • Offset facilities
  • Household income
  • Available cash flow
  • Existing debts
  • Banking arrangements
  • Financial objectives
  • The way money moves throughout the month

Where an alternative lending structure may be appropriate, the potential benefits, costs, risks and suitability need to be assessed carefully.

The objective is to create an efficient structure around your circumstances — not simply change loans for the sake of refinancing.

6

Does your strategy mean I need to earn more money or dramatically change my lifestyle?

Not necessarily — and that's one of the key principles behind our approach.

Before asking, “How can you pay more?”, we ask a different question:

“Can the money you're already earning be working more efficiently?”

We analyse how your existing income and household cash flow interact with your mortgage.

There may be opportunities to improve efficiency by changing where income is held, how expenses are managed, how available cash interacts with your mortgage and how your overall lending structure is configured.

Good financial discipline remains important, but our objective isn't to build a strategy that depends on an unrealistic lifestyle.

We want your existing money working harder before asking you to work harder for more money.

7

Will everyone achieve the same result?

No — and we believe it's important to be completely clear about that.

Every household is different.

Your potential outcome will depend on factors including your:

  • Mortgage balance
  • Interest rate
  • Loan structure
  • Household income
  • Living expenses
  • Existing debts
  • Available cash and savings
  • Financial behaviour
  • Lending eligibility
  • Personal circumstances

That's why we don't believe in promising everyone the same saving or the same Mortgage Freedom date.

We model the opportunity around your numbers and your circumstances.

8

How will I know whether the strategy could actually work for me?

That's exactly what our assessment is designed to determine.

We analyse your current mortgage and financial position and compare it with potential alternative structures and cash-flow strategies.

This allows us to help you understand:

  1. Where you are today
  2. How your current mortgage is structured
  3. How your money currently flows
  4. Where potential inefficiencies may exist
  5. What an alternative structure could potentially look like
  6. Your potential pathway towards Mortgage Freedom

Rather than asking you to believe in a generic strategy, we want you to understand what the numbers may look like for you.

9

What is the Amortize Debt “Debt Chain”?

The Debt Chain is our methodology for looking at your finances as one interconnected system rather than a collection of unrelated accounts.

Your mortgage, income, offset account, everyday spending, other liabilities and available cash flow all interact.

We analyse how money enters that system, where it sits, when it leaves and how efficiently it is being used.

The objective is to identify opportunities to structure that financial chain so that your money is working towards reducing the effective cost and duration of your mortgage wherever reasonably possible.

Put simply:

It's not only about how much money you have.

It's about how efficiently that money is working.

10

Will Amortize Debt simply set up a strategy and leave me to manage it?

No. Our service is designed around implementation, monitoring and ongoing support.

Creating the strategy is only the beginning.

We help clients understand the structure, implement the agreed strategy, monitor their progress and remain accountable to their Mortgage Freedom objective.

Where circumstances change — income, expenses, interest rates, lending arrangements or other relevant factors — the strategy may also need to be reviewed.

We're not focused on completing a short-term program. We're focused on helping you remain on the pathway towards becoming Mortgage Free.

11

How much sooner could I potentially become Mortgage Free?

That's the question we ultimately want to help you answer.

But we don't believe in giving you a generic number before we understand your financial position.

The potential difference can depend on your mortgage, interest rate, loan structure, income, expenses, available cash flow and how consistently an appropriate strategy can be implemented.

That's why we start with your actual numbers.

We'll assess your existing position and model what may be achievable under an appropriate alternative strategy.

Don't ask, “Does this work for everyone?”

Ask, “What could this potentially mean for my mortgage?”

That's what your Mortgage Freedom Assessment is designed to help you discover.

See Your Money Working Harder

Your Mortgage Freedom Journey

Understand how your mortgage structure and cash flow interact, see where potential efficiencies may exist, and track your progress towards Mortgage Freedom. Most homeowners know their mortgage balance.

Far fewer know what their current loan structure could ultimately cost them — or whether there may be a more efficient way to manage it.

At Amortize Debt, we help you understand how your mortgage, income and household cash flow work together — and identify opportunities to structure them more efficiently. Then we give you the tools and ongoing visibility to see how you're progressing towards one clear objective:

Mortgage Freedom Dashboard

Cash-Flow Visibility

Mortgage Progress Tracking

Personalised Mortgage Freedom Date

Interest Impact Monitoring
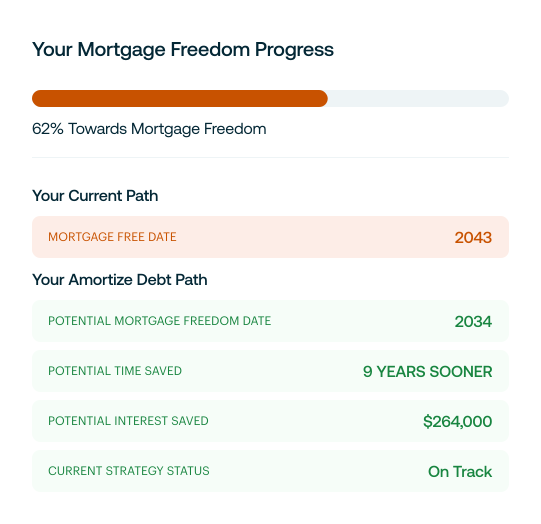
* Illustrative example only. Actual outcomes vary according to individual circumstances, loan structure, interest rates, cash flow and other factors.